Initial Communication
EDW and the client identify and discuss the characteristics of the desired pool to be securitised.
Deals Selection
EDW selects a list of deals based on completeness of data, results of data quality checks, and pool characteristics discussed.
The list of deals is then shared and modified based on client feedback.
Proxy Loans Selection
A subset of the underlying loans (based on the characteristics portfolio to be securitised) from the selected deals are taken as proxy loans. Their historical performance data is compiled.
Data Adjustments
A Dataset from each selected deal is scrutinised further for quality.
Any idiosyncratic reporting practices in a deal are adjusted to one standard, and any outlying results are investigated and discussed with the relevant EDW analyst.
Final Performance Dataset
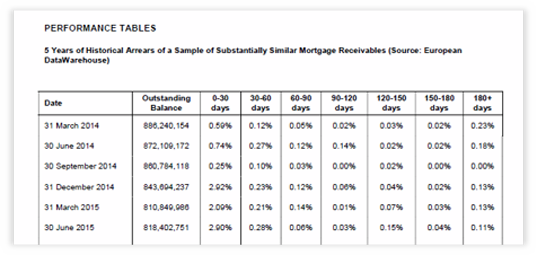
The final performance dataset is delivered including static Default/Loss and Dynamic Arrears information.
Static pools are based on the year of securitisation.
Since each portfolio has a unique set of characteristics, EDW applies principles of good judgement.
RESULT: Proxy Data Sample
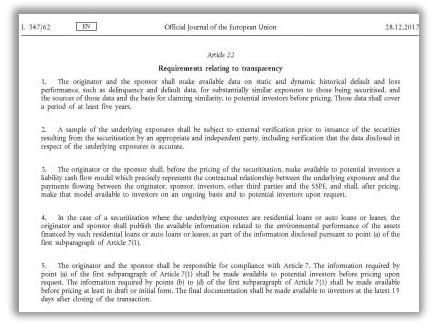
Originators & sponsors can provide static and dynamic historical default and loss performance data for substantially similar exposures to those being securitised for a period of at least five years.