Collaborative data solution for the asset-backed securities market
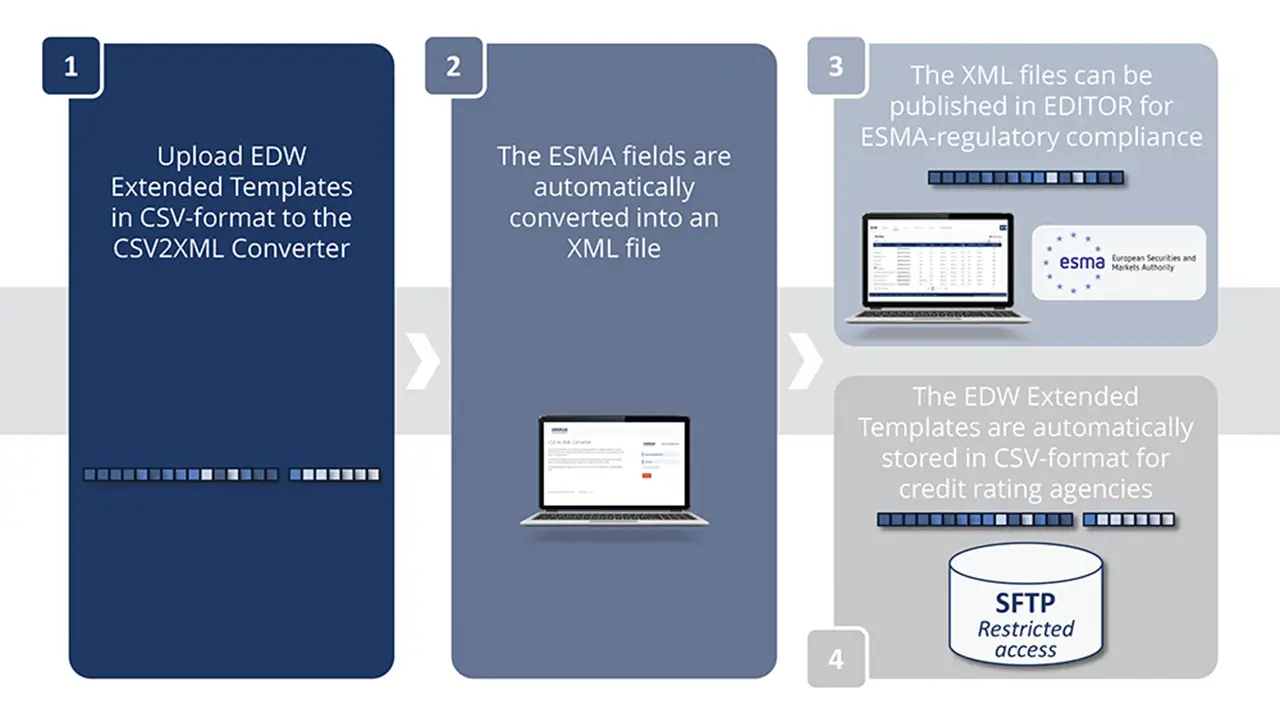
EDW’s Extended Templates were born following the publication of ESMA’s underlying exposure templates.
The templates, however, no longer comprised valuable data fields required by rating agencies and market participants to update their credit and cash flow models.
EDW responded to this by launching a project with each of the four leading rating agencies, (DBRS Morningstar, Fitch Ratings, Moody’s Investors Service, and S&P Global Ratings) to introduce extended ESMA reporting templates for all asset classes and the investor reports.
The process took more than a year, whereby EDW approached each of the rating agencies separately to identify the fields previously included in the ECB templates which would still be needed to properly assess a transaction following the introduction of the ESMA templates.
In total, our teams identified and incorporated the following additional fields by asset class into the EDW Extended Templates: